In the last ten years, the way we handle money has shifted dramatically. Traditional debit and credit cards have been replaced by digital wallets. These software-based platforms securely store payment information and allow users to make transactions electronically. From paying for groceries with a tap of a smartphone to sending money across borders instantly, digital wallets are redefining convenience and accessibility in the financial world.
In the following article, Michael W. Brescia explores what digital wallets are, how they work, their benefits, potential drawbacks, and the future of this rapidly evolving technology.
The Digital Wallet
A digital wallet is essentially a virtual version of your physical wallet. Instead of carrying cash, debit cards, or credit cards, you can store your financial information securely on your smartphone, tablet, watch or computer. Most digital wallets allow users to:
- Make purchases online or in-store
- Send or receive money instantly
- Store loyalty cards, gift cards, and coupons
- Track spending and manage budgets
Popular examples include Apple Pay, Google Wallet, Samsung Pay, PayPal, Venmo, and numerous banking apps that integrate wallet features directly. Many fintech companies are also developing niche wallets tailored for specific use cases, such as cryptocurrency transactions or international money transfers.
How They Work
Digital wallets operate by storing encrypted payment information and connecting with payment processors or banking networks. When a transaction occurs, the wallet communicates with the merchant’s system to authorize the payment without revealing sensitive information like card numbers. Features such as tokenization and biometric authentication (fingerprint or facial recognition) add an extra layer of security, making digital wallets safer than carrying physical cards in many scenarios.
Most wallets can function via:
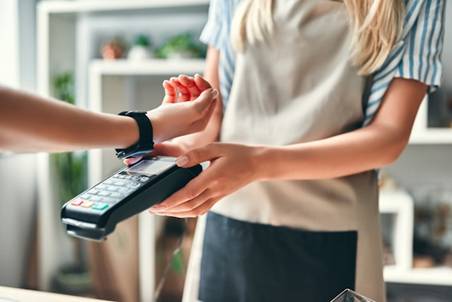
Near-Field Communication (NFC) – For tap-and-pay transactions at physical stores.
QR Codes – Users scan codes to complete payments, common in Asia and increasingly worldwide.
Online Integration – Automatically filling payment information during online checkouts.
The Benefits
The rise of digital wallets has been fueled by convenience, security, and functionality. Some key advantages include:
Convenience and Speed
With a digital wallet, users can complete transactions in seconds. There’s no need to fumble with cash, search for a card, or manually enter payment details online. Many wallets also allow users to store multiple cards and switch between them instantly.
Enhanced Security
Digital wallets are often more secure than carrying cash or physical cards. Tokenization ensures that actual card numbers are never transmitted during a transaction. Additionally, features like biometric authentication and two-factor authentication reduce the risk of fraud.
Access to Rewards and Loyalty Programs
Many wallets integrate directly with loyalty programs, cashback offers, and coupons, streamlining savings opportunities. Users can automatically earn points or redeem rewards without carrying additional cards.
Budgeting and Expense Tracking
Some digital wallets provide insights into spending patterns, helping users monitor expenses and manage budgets more effectively. Notifications of transactions in real-time also give greater control over personal finances.
Peer-to-Peer Transfers
Digital wallets simplify sending money to friends or family. Instead of writing checks or going through bank transfers that can take days, users can transfer funds instantly with minimal fees.
Global Transactions Made Easier
For international travelers or businesses, digital wallets can facilitate cross-border payments, often with lower fees than traditional banks. Currency conversion and international payment support are increasingly common features.
Drawbacks
Despite their growing popularity, digital wallets are not without limitations and risks. Awareness of these drawbacks is essential.
Dependence on Technology
Digital wallets require a smartphone, tablet, or other compatible device, along with internet connectivity. If your device is lost, stolen, or malfunctions, access to funds can be temporarily disrupted.
Privacy Concerns
While digital wallets use encryption, they also collect data on spending habits. Some users may feel uncomfortable with companies tracking transactions, and there is always the risk of data breaches.
Merchant Acceptance
Although acceptance is growing, not all merchants, especially small businesses, support digital wallet payments. In some regions or industries, cash and card payments may still be necessary.
Security Risks
Despite added protections, no system is entirely immune to hacking or fraud. Phishing scams, malware, or device theft can compromise wallet security if users are not vigilant.
Transaction Limits and Fees
Some digital wallets impose limits on transaction amounts, withdrawals, or transfers. Additionally, certain peer-to-peer or international payments may involve fees, which can add up over time.
Dependency on Battery Life
Unlike cash or physical cards, a digital wallet cannot function if your device battery dies. This makes carrying a backup payment method advisable.
Practical Applications
Digital wallets are versatile tools that extend beyond basic payments. Some practical applications include:
Retail purchases: Tap-to-pay in stores, pay at restaurants, or shop online seamlessly.
Public transportation: Many cities now accept digital wallet payments for buses, trains, and subways.
Peer-to-peer transfers: Splitting bills or sending money instantly to friends and family.
International remittances: Sending money across borders at lower fees and faster speeds.
Cryptocurrency transactions: Some wallets support Bitcoin, Ethereum, and other digital currencies for payments and trading.
Event and ticketing integration: Mobile tickets and passes stored within wallets reduce paper clutter and streamline check-ins.
The Future of Virtual Banking
Emerging trends include:
Integration with AI and personalization: Some wallets offer personalized financial insights, spend recommendations, and smart budgeting tools.
Expansion of cryptocurrency and digital assets: More wallets are supporting cryptocurrencies, NFTs, and other blockchain-based assets.
Greater interoperability: Digital wallets may soon allow cross-platform transactions without restrictions, improving convenience.
Enhanced security measures: Innovations like behavioral biometrics and AI-driven fraud detection are improving protection.
Financial inclusion: Fintech companies are developing wallets aimed at underserved populations, helping reduce barriers to banking.
Tips for Safe Digital Wallet Use
To maximize the benefits while minimizing risks, users should follow these best practices:
Enable strong authentication: Use biometrics, PINs, or two-factor authentication.
Update software regularly: Keep wallets and devices updated to patch security vulnerabilities.
Monitor account activity: Check transactions frequently for any unauthorized charges.
Use reputable wallets: Stick to well-known providers with strong security measures and transparent policies.
Have backup payment options: Carry a card or cash in case of technical issues.
Avoid public Wi-Fi: Use secure networks for transactions to prevent interception of sensitive data.
Integrating Technology into All Aspects of Life
Digital wallets are revolutionizing the way we pay, send money, and manage finances. Their convenience, security features, and integration with financial tools make them a compelling alternative to cash and traditional card-based payments. However, users must remain mindful of potential drawbacks, including technology dependence, privacy concerns, and merchant acceptance limitations.
As digital wallets continue to evolve, they are likely to become even more deeply integrated into daily life, from retail transactions to international remittances and cryptocurrency management. By understanding both the benefits and risks, consumers can leverage digital wallets effectively while navigating the complex and rapidly changing landscape of modern financial technology.